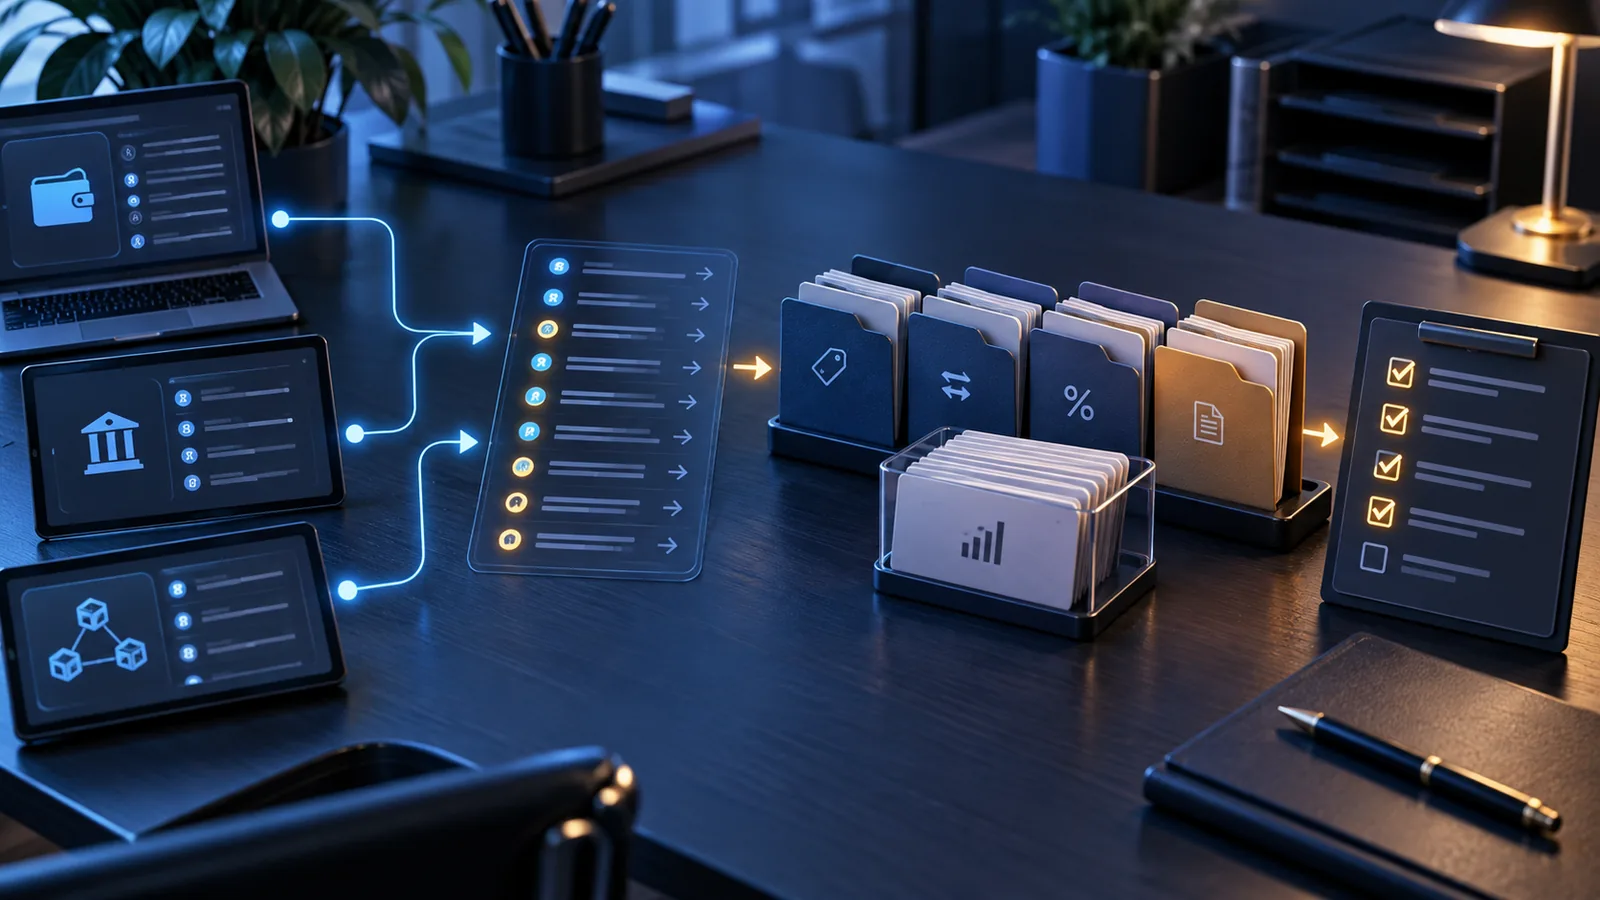
Regularly export histories from every platform and wallet, retain price and fee evidence, and link internal transfers with transaction identifiers. Taxable events, valuation methods and reporting duties depend on jurisdiction and personal status.
Every source must be reconciled.
Date, asset, quantity, value and fees.
An internal transfer should not be assumed.
Inventory every source
List platforms, wallets, blockchains, bank accounts and discontinued services. Export native files before closure and record the period, timezone and unit used by each statement.
Normalize operations
For each movement, keep timestamp, nature, sent and received asset, quantity, reference value, fees, address and transaction ID. Keep failed operations if they incurred fees.
- Retain the raw file
- Work on a normalized copy
- Document manual corrections
Reconcile internal transfers
A withdrawal from a platform may match an entry in your wallet and not be a disposal. Link both sides by network, amount, time and ID while accounting for fees and wrapped tokens.
Apply local rules
Identify tax residence, private or business status, taxable events, cost method and retention periods. Seek qualified advice for complex cases, especially DeFi, staking, airdrops, bridges and losses.
- Check the current rule version
- Keep calculation and source
- Archive the filing and evidence
Minimum record per operation
| Field | Example evidence | Purpose |
|---|---|---|
| Timestamp | Export and explorer | Order and reporting period |
| Quantities | Raw statement | Inputs, outputs and balance |
| Valuation | Dated method and source | Calculation basis |
| Fees | Receipt and transaction | Cost or expense under local rules |
Frequently asked questions
Is a block explorer enough?
No. It shows on-chain movements but not always identity, acquisition price or internal platform trades.
Should raw files be kept?
Yes. They allow recalculation and support the origin of a correction.
Is this tax advice?
No. It is a general record-keeping method; rules must be checked in each jurisdiction.
Verifiable sources
 OECD — Crypto-Asset Reporting Framework
 ESMA — Crypto-assets and investor information
 Bitcoin.org — What you need to know
Independent educational content reviewed against primary documentation. No personalized recommendation or promise of returns. Reviewed September 21, 2026